Mortgage FAQ · Florida
Florida mortgage questions, answered
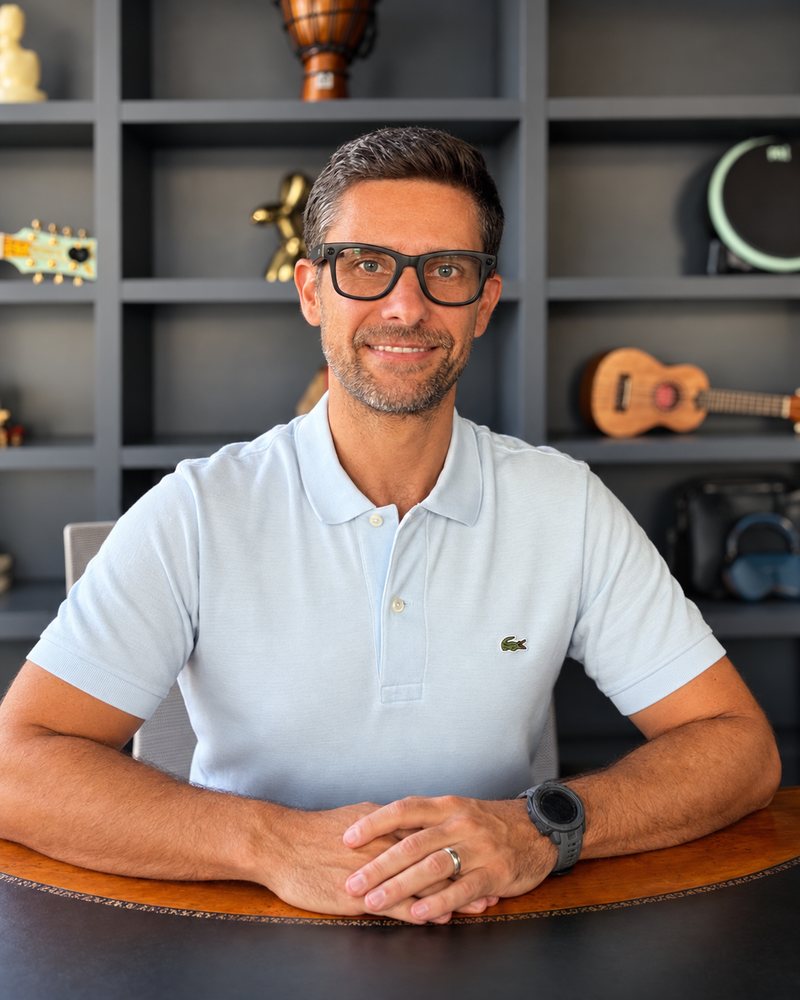
Straight answers from Darryn Stephen, Senior Mortgage Advisor.
These are the questions I hear most from buyers, homeowners and realtors. Don’t see yours? Text me.
- Florida-licensed
- NMLS #2664300
- Smart Home Loans NMLS #1734077
General
What does a Mortgage Advisor do?
A mortgage advisor works with a range of lenders and loan programs and helps match a borrower to options that may fit. Darryn Stephen is a Senior Mortgage Advisor with Smart Home Loans (NMLS #2664300; company NMLS #1734077).
How do I verify a mortgage advisor’s license?
Search the NMLS number at nmlsconsumeraccess.org. Darryn Stephen is NMLS #2664300 and Smart Home Loans is NMLS #1734077.
Where is Darryn Stephen based?
Jupiter, in northern Palm Beach County, Florida. He serves Jupiter, Tequesta, Palm Beach Gardens, North Palm Beach, West Palm Beach, Stuart and Martin County, Port St. Lucie and buyers across Florida.
What’s the difference between pre-qualification and pre-approval?
Pre-qualification is a quick estimate. Pre-approval usually involves reviewing documents like income, assets and credit, so it carries more weight with sellers. Neither is a commitment to lend.
Does Darryn quote interest rates online?
No. Rates and terms depend on your credit, the property, the loan and the market on the day you lock, so Darryn gives you real numbers in a conversation, not on a website.
VA loans in Florida
Do I need a minimum credit score for a VA loan?
Credit guidelines for VA loans are set by each lender, not the VA itself. Low credit scores are welcome. Darryn reviews your full picture and looks for a lender whose guidelines may fit, depending on lender and program.
Do I need a down payment for a VA loan in Florida?
Eligible veterans and service members with full entitlement may not need a down payment. You may still have closing costs, though sellers may contribute up to 4% in concessions plus normal closing costs.
What is the VA funding fee?
It’s a one-time fee that helps fund the VA program. It can usually be rolled into the loan. Veterans receiving VA disability compensation and some surviving spouses are generally exempt.
Can I use a VA loan for a condo in Palm Beach County?
Yes, if the condo project is VA approved or can get approved. Darryn checks this early so it doesn’t hold up your closing.
Can a surviving spouse use VA home loan benefits?
Some surviving spouses are eligible for a VA loan, depending on the circumstances. The Certificate of Eligibility process confirms it.
Can I use my VA loan more than once?
Yes. VA entitlement can be restored after you sell and pay off a VA loan, and in some cases remaining entitlement may let you have a second VA loan.
First-time buyers & down payment assistance
What counts as a first-time home buyer in Florida?
For many programs, it means you haven’t owned your primary home in the past three years. Florida Hometown Heroes waives the first-time buyer rule for active duty military and veterans. Rules vary by program.
Who qualifies for Florida Hometown Heroes?
Full-time employees of a Florida-based employer in eligible fields such as healthcare, K-12 school staff, first responders, public safety and court employees, child care workers, plus military members and veterans, who meet income, credit and program limits. Funding is limited.
Is down payment assistance free money?
Usually not. Florida Hometown Heroes and FL Assist are second mortgages with no interest, deferred until you sell, refinance, pay off the first mortgage or move out, when they must be repaid. Program terms set by Florida Housing and subject to change. Some county programs may be forgiven after years of living in the home. Each program is different.
Can I use down payment assistance in Palm Beach County?
Possibly. Statewide Florida Housing programs work across the county, and Palm Beach County runs its own programs when funding is open. Income, price limits and funding windows apply.
How much do I need to save to buy my first home?
It depends on the loan, the price and any assistance or seller credits. You may still need money for earnest deposit, inspections and some closing costs. Darryn maps out your likely cash needed up front.
Do I need homebuyer education?
Many assistance programs and some low down payment loans require a homebuyer education course. It’s usually online and quick.
FHA loans in Florida
What credit score do I need for an FHA loan?
FHA guidelines are generally flexible on credit scores, and the minimum down payment may depend on your score. Many lenders set their own minimums, so options depend on lender and program.
Can my down payment be a gift?
Yes, FHA allows gifts from eligible sources such as family, with a gift letter and documentation of the transfer.
Can the seller pay my closing costs on an FHA loan?
Sellers may contribute up to 6% of the sales price toward eligible closing costs, prepaids and buydowns.
Does FHA mortgage insurance ever go away?
It depends on your down payment and loan terms. In many cases it stays for the life of the loan unless you refinance. Darryn will explain how it applies to you.
Is FHA only for first-time buyers?
No. FHA is for primary residences, and repeat buyers can use it too.
Conventional low down payment
Do I need a large down payment for a conventional loan?
No. Many conventional loans allow a smaller down payment, and eligible buyers may qualify for low down payment programs like HomeReady and Home Possible. Requirements depend on lender and program.
Can I remove PMI later?
Generally yes. Private mortgage insurance on a conventional loan can usually be removed once you reach enough equity, depending on the loan and servicer rules.
Is conventional better than FHA?
It depends on your credit, down payment and plans. Stronger credit often favors conventional; building credit often favors FHA. Darryn compares both for you.
Can I use a conventional loan for a condo?
Yes, if the condo project meets conventional guidelines. Florida condo reviews look closely at reserves, insurance and inspections, so Darryn checks early.
Seller concessions & rate buydowns
How much can a seller contribute on a conventional loan?
On a primary or second home, the cap is 3%, 6% or 9% of the price depending on your down payment, with higher caps as the down payment grows. On an investment property, 2% regardless of down payment.
How much can a seller pay on an FHA loan?
Up to 6% of the sales price. FHA allows a low down payment, and the minimum may depend on your credit score.
How much can a seller contribute on a VA loan?
Up to 4% in seller concessions, plus normal closing costs on top of that.
How much can a seller contribute on a USDA loan?
Up to 6% of the sales price.
Do buydowns count toward the seller concession cap?
Yes. Seller-paid rate buydowns and discount points count toward the cap.
Can I get cash back from a seller credit?
No. Seller credits can only cover eligible closing costs, prepaids and buydowns, and can’t exceed what those actually cost.
Refinance, cash-out & HELOC
When does refinancing make sense?
When the long-term savings outweigh the closing costs over the time you expect to keep the loan, or when you need to change the loan for another reason, like removing a co-borrower. Darryn runs a break-even comparison.
Is a HELOC or cash-out refinance better?
A HELOC keeps your current first mortgage; a cash-out refinance replaces it. Which may fit depends on your current loan, how much you need and how long you need it. Sometimes neither is the best option.
Should I use a HELOC to pay the IRS?
Not always. An IRS payment plan may cost less than a HELOC, depending on your situation. Talk to Darryn and your tax professional before you borrow.
Can I remove my ex from the mortgage without refinancing?
In most cases a refinance or sale is needed, because the lender doesn’t release a borrower just because of the divorce decree. Some loans may allow an assumption. Darryn works with your attorney. Not legal advice.
Self-employed & bank statement loans
Can I get a mortgage if I’m self-employed in Florida?
Yes, many self-employed borrowers qualify. Lenders usually want a history of self-employment, often two years, and document income through tax returns, or with some programs, bank statements.
What is a bank statement loan?
A non-traditional loan that may use 12 or 24 months of bank deposits to calculate income instead of tax returns. These often need a larger down payment and may cost more, depending on lender and program.
How long do I need to be self-employed?
Often two years, though some lenders may accept less with prior experience in the same field. It depends on lender and program.
Will my write-offs hurt my mortgage?
On a traditional loan, lenders generally use income after deductions, so big write-offs can lower qualifying income. That’s why alternative documentation may help.
Local questions
Can I buy a second home in Tequesta with a conventional loan?
Yes, second homes can be financed with conventional loans, with their own down payment and occupancy rules. Options depend on lender and program.
Do I need flood insurance in Tequesta?
If the home is in a high-risk flood zone and you have a mortgage, lenders generally require flood insurance. Many waterfront homes are. Darryn helps you plan for the cost early.
Do you meet clients in Tequesta?
Yes. Darryn is based in nearby Jupiter and can meet locally, or work by phone and video.
Do you work with buyers in Martin County?
Yes. Darryn is based in Jupiter, just south of Martin County, and works with buyers in Stuart, Palm City, Jensen Beach, Hobe Sound and Hutchinson Island.
Are there USDA loans in Martin County?
Some areas outside the main city centers may be USDA eligible. Eligibility depends on the property address and household income limits.
What should I know about buying a Hutchinson Island condo?
Lenders review the condo association’s budget, reserves, insurance and inspection status. Some buildings may not meet guidelines, so Darryn checks the building early.
Should I use the builder’s lender in Port St. Lucie?
Builder incentives can be valuable, but they sometimes depend on using the builder’s lender. Darryn helps you compare the full cost so you can decide.
Can I use down payment assistance in Port St. Lucie?
Statewide Florida Housing programs such as Florida Hometown Heroes and FL Assist may be used in St. Lucie County, and the county may run its own SHIP purchase assistance when funded.
Can I use a VA loan on a new build?
Yes, VA loans can finance new construction from many builders, subject to VA appraisal and lender requirements.
Programs, guidelines and eligibility change and vary by lender and program. This page is general information, not a commitment to lend or a guarantee of approval. All loans are subject to credit approval, underwriting and property approval. Not legal or tax advice.
Let’s talk it through
No pressure, just clear answers about what may fit you. Call, text or email me.
Ready to apply? Start at smarthomeloans.net.